CheckValue

The complaint arrives in the same shape every time. You sent the website the right square footage and got an automated reply. The listing page will not let you claim the house. The file still names the couple you bought from three years ago. Usually you are simply writing to the wrong desk: the facts about your house live in a handful of records, each with its own keeper, and only some of those keepers owe you anything.
Why nothing changed after you reported the error
The number you are looking at sits at the end of a copy chain. A county office keeps a characteristics file for taxation. Data vendors license or harvest it, blend it with listing feeds and sell the result. Websites recompute on top of that vendor copy, nightly or weekly, moving older sales forward with a price index such as the FHFA House Price Index, published down to ZIP code and census tract level4.
Two consequences follow. A correction typed into the last link of that chain gets overwritten by the next refresh of the first link, which is why your edit disappeared. And the only keeper with a published duty of accuracy sits at the start, because its file decides a tax bill; everything downstream is a copy, and a copy owner can decline your letter without breaking any rule. Why the same house changes value between two refreshes is told in why a home value jumps from week to week.
Which record holds which fact, and who can change it
Before you write another email, name the record you are actually trying to fix.
| Record | Kept by | What it decides | How a correction starts | Realistic speed |
|---|---|---|---|---|
| Deed and chain of title | County recorder or registrar | Who owns the property and its legal description | Record a corrective deed or affidavit, usually with an attorney | Days once it is recorded |
| Characteristics file and assessment roll | Assessor or appraisal district | Living area, rooms, year built, class, assessed value | Characteristics correction, or a grievance with evidence2 | One assessment cycle |
| Mailing and taxpayer name | Assessor or treasurer | Where the tax bill goes, which name is displayed | Excise tax form filed with the recorded documents; owner-name errors through the recording office3 | Weeks after recording3 |
| Lender's appraisal or evaluation | The lender's loan file | The value used for your mortgage | Written request for a reconsideration of value1 | Days, inside the loan |
| A website's estimate | A private company | A published number and a lead | A claim or edit form, if the site offers one | No commitment at all |
The first four rows have a procedure, a counterparty and a paper trail. The fifth has a contact form, and spending three months on it is how this complaint turns into a lost year. What the number is supposed to mean in the first place is set out in the guide to home value.
"Can't claim my home": what claiming does and does not change
Claiming an address usually proves to a site that you control the property, so that facts, photos and your contact details can be attached to its file. Read it as a marketing permission rather than a correction right. Three things it does not do: it does not reach the county, so the next estimate built on county data repeats the old figure; it does not oblige the model to use your entry, which can be capped or weighted at zero; and it does not survive a feed refresh from the vendor copy.
There is a simpler test than arguing about the model. After your edit, open the assessor's property card for your parcel and look at the same field. If it still shows the old figure, nothing has been corrected, whatever the website now displays. The same business model explains the phone field, a pattern covered in why the free online valuation asks for your number.
How to get the square footage and room count corrected at the source
The assessor's characteristics file is the fact base almost every estimate inherits, so that is where a correction earns its keep. Six steps, in order.
- Pull your property card. Most assessors publish it by parcel number. Print it and mark every wrong field: living area, bedrooms, bathrooms, year built, lot size, class.
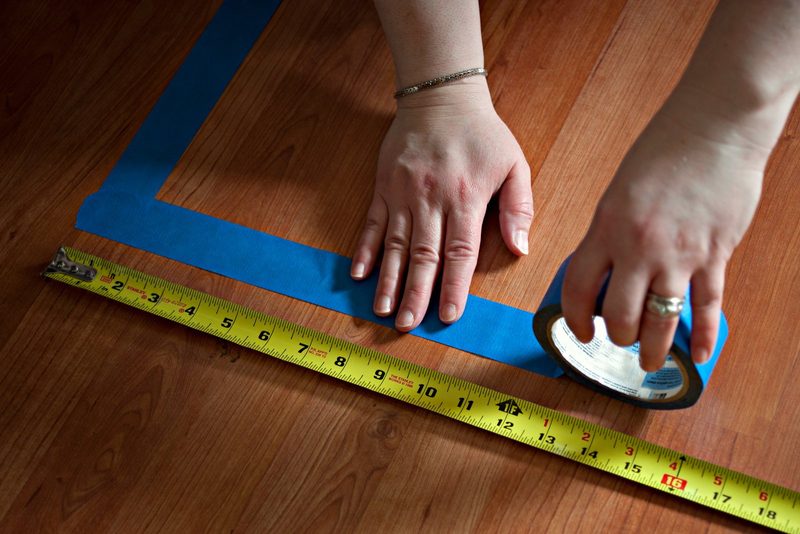
- Measure. Tape or laser along the outside walls, floor by floor, with the dimensions written on a sketch. Keep finished above-grade area separate from basement and garage.
- Collect proof. Permits and their sign-off, the recorded deed or plat for the lot, dated photos, builder plans, any appraisal you already paid for.
- Call the office before you file. Clerical errors often get fixed at the counter, and the conversation tells you which form and which window apply to your parcel.
- File inside the window. In New York anyone who pays the property taxes may grieve, only the current tentative roll can be grieved, and owners outside New York City and Nassau County file Form RP-524 with the assessor or the board of assessment review by Grievance Day, usually the fourth Tuesday in May, at no cost and without a lawyer2.
- Get it in writing. You may attend the hearing and present statements and documentation, and the board's notice has to state the reasons for its determination2. That notice is what the next office will read.
A corrected characteristics file then feeds every future estimate built on county data, which is the point of filing. The assessed value on the roll stays a tax figure rather than the market value of your home, a difference laid out in assessed value versus market value.
Two deadlines decide the year. Miss Grievance Day and the administrative and judicial review of that assessment are gone until the next roll2. And a correction can cut both ways: raising a recorded living area can raise the assessed value and the tax bill with it, so read the figures before you file. This is general information, not legal or tax advice.
"It still shows the previous owner after three years"
A few weeks of lag is normal. Snohomish County states where its owner names come from: the Real Estate Excise Tax form filed with the recorded documents, a copy of which reaches the assessor once the sale is recorded and the tax paid, with a few weeks to process it3.
Three years means something is missing rather than slow. The usual causes: the deed was never recorded, or recorded in the name of a trust or a company so no natural person appears; a marriage or divorce changed the name without a new recorded instrument; only a portion of the parcel actually sold, which the same county warns can delay the change even longer3; or the site you are reading cached a roll it never refreshed.
Follow the paper. Order the recorded deed from the recorder, read the grantee name, compare it with the assessor's display. Which desk owns the fix varies by county, so ask: Snohomish County sends errors in the owner's name to the Auditor's Office and errors in the physical description to the Assessor's Office3. A deed that is itself wrong needs a corrective instrument recorded, which is attorney territory. The routes into each register are mapped in how to find out who owns a property and in property records explained. This is general information, not legal or tax advice.
Inside a mortgage, your evidence has a named channel
Joint guidance published on 26 July 2024 by five federal agencies (the Federal Reserve Board, the FDIC, the NCUA, the OCC and the CFPB) describes how a lender sends a valuation back to whoever prepared it, a step the agencies call a reconsideration of value1. One line in it was written for exactly this complaint: the request may cover property characteristics, or other information about the property, that was reported incorrectly or never considered, as well as comparable properties nobody identified the first time1. A valuation also counts as deficient when it carries errors or omissions, not only when the figure disappoints1.
Two of the example policies the agencies list work in your favor: telling borrowers how to raise concerns while an error can still be fixed before the credit decision, and testing whether the institution's own requirements discourage people from asking at all1. Two caveats. The guidance binds nobody, being supervisory and imposing no new requirements, and it reaches home loans on properties of one to four units only1. Regulation B hands you the paper: every appraisal and written valuation on a first-lien home loan, at no charge, with written notice of that right due within three business days of your application5. The full route is set out in what to do when the valuation visit runs late or feels rushed. This is general information, not legal or tax advice.
When nobody answers: the escalation ladder
Work upwards, keeping every answer in writing.
- The assessor. Ask for the determination in writing and for the evidence behind it. In New York the next rungs are the board of assessment review and then judicial review2.
- The lender. Write, do not phone. The 2024 guidance expects a bank to identify, escalate and settle valuation complaints however they arrive, and to decide whether a reassessment follows1.
- The appraiser. Discipline sits with the state appraiser boards. The Appraisal Subcommittee's hotline on 877-739-0096 answers one question, which state or federal agency should receive a USPAP or independence complaint; the Subcommittee has no legal authority to investigate and the hotline stays out of the process and the outcome6.
- The website. No regulator will order a marketing estimate corrected for you. The pressure point sits upstream in the public record, which is why the filing steps come before the complaining.
Worked example: 270 square feet missing on an upstate New York house
The figures below are a hypothetical example at upstate New York price levels, not a real transaction. The roll records 1,580 sq ft; the owner measures 1,850 sq ft of finished above-grade area, the gap being a permitted 1997 addition that never reached the card. A comparable sale two streets away closed 14 months ago at $410,000, and FHFA's release of 29 September 2026 puts the Middle Atlantic census division up 6.3 percent over the twelve months to July 20267, so that sale carried forward lands near $436,000 before adjustments.
| Step | Example date | Record touched | Result |
|---|---|---|---|
| Edit submitted on a listing site | March | None | Display changed for a week, then refreshed back |
| Property card pulled, house measured, permit retrieved | April | None yet | Evidence pack of sketch, permit and photos |
| Informal review with the assessor's staff | Early May | Characteristics file | Staff accept the sketch, ask for the permit number |
| Form RP-524 filed by Grievance Day | Fourth Tuesday in May2 | Assessment roll | Written decision with reasons2 |
| New valuation run on the corrected facts | June | The owner's own report | Range built on 1,850 sq ft and four-bedroom comps |
The arithmetic behind the last line is plain. At a marginal $150 per square foot for added finished area in this example, 270 square feet is about $40,500, close to a tenth of a value near $425,000. The second effect is larger and harder to see: with the corrected area and room count, the comparable search returns different houses, so the evidence base changes too. That failure has its own page, what to do when the facts or the comps are wrong.
Where your own facts enter a CheckValue report, and what stays out of reach
CheckValue runs the sequence in the opposite order to the one that produced this complaint. No file about you starts the calculation: after the address you set the numbers yourself, living area, rooms, year built, lot and condition, plus the property type and your own photos if you want them read. The report layout appears on screen as a free preview before any payment, which you can open at the address field, and the calculated version prints the comparable sales with each adjustment, its coefficient and its source, so you can see which entry moved the result. Entered something wrong? Change it and calculate again, since purchased reports do not expire; prices are on the pricing page. The promise behind the purchase is deliberately small: no report despite payment, or wrong address? The report is credited back automatically, or we refund within 30 days.
The limits are equally concrete. No register moves because a report says so, neither the assessment roll nor the recorded deed nor another company's copy of your data; those change on your filing at the offices named above. Nobody arrives with a tape measure either, so the area you confirm is the area the calculation values. The document is an AI valuation report built on cited public data, while a licensed appraiser's opinion is a different instrument: where a bank, a court or a tax office demands one, use the report to prepare for that step rather than in its place. US addresses additionally carry the owner of record taken from public county files, and those details may not be used for credit, employment, insurance or tenant-screening decisions, which is where federal law reserves the consumer report furnished by a consumer reporting agency8. The path from your confirmed facts to a range is traced in how an AI valuation works.
In Tenerife and in Austria I have spent more mornings at registry counters than I can count, and the lesson never changes: a clerk corrects a file on the day you put proof on the desk, never on the day you only complain.
Keep one folder for the house: the measured sketch, every permit, the recorded deed, the plat, dated room photos and all correspondence. It serves a grievance, a lender request, a buyer's appraiser and your own next valuation run.
Frequently asked questions
I reported wrong information and nothing changed, what now?
Work out which record you actually reported it to. A private website keeps a copy of public data and answers to nobody for that copy. The assessor's file and the assessment roll have a published correction route, your county recorder holds the deed, and a valuation your lender ordered can be sent back for a reconsideration of value. Send your evidence to one of those three, in writing, and ask for a written determination.
Why won't a website let homeowners update their home information?
Editing fields cost money to build and to police, and a site that recalculates nightly from licensed county and listing feeds would overwrite whatever you typed at the next refresh. The free number also earns its keep as a lead or an ad impression rather than as a paid product, so there is no service promise behind it. The record that the law expects to be accurate is the public one.
Why can't I claim my home on a property website?
A claim usually proves that you control the address so the site can attach marketing facts and your contact details to the file. It is not a correction right. Nothing you enter travels to the county, the model may weight your entry at zero, and the next data refresh can drop it. Check afterwards whether the public record changed, because that is the copy every other estimate reads.
Why does the record still show the previous owner after three years?
Three years is not processing lag. Snohomish County explains that the owner name on its site comes from the real estate excise tax form filed with the recorded documents, and that staff need a few weeks, longer when only a portion of a parcel actually sold. After that long, something is missing: a deed never recorded, a transfer into a trust or company name, a marriage or divorce that changed the name without a new recorded instrument, or a vendor caching an old roll.
I asked them to fix the square footage, who is actually responsible?
The assessor's office, because it keeps the characteristics file that nearly every estimate starts from. Pull the property card, measure the outside walls, sketch each floor, collect permits, and file the correction in the window your state gives you. In New York that is Form RP-524 with the board of assessment review by Grievance Day, usually the fourth Tuesday in May, at no cost and without a lawyer.
Can I force a lender to look at a valuation again?
Force is the wrong word, but the route exists. Joint guidance from the five federal banking and consumer agencies tells institutions to capture valuation complaints, to explain how a borrower raises concerns while an error can still be fixed before the credit decision, and to test whether their own hurdles put people off asking. Write to the lender, name the wrong characteristic, attach the proof, and keep the reply.
Who do I complain to about an appraiser's errors?
State appraiser boards license and discipline appraisers. The Appraisal Complaint National Hotline run by the Appraisal Subcommittee will tell you which one: it gives callers the contact details of the state or federal agency that should receive a complaint about a USPAP violation or about appraisal independence, on 877-739-0096. The Subcommittee has no legal authority to investigate complaints, and the hotline does not intervene in the process, the investigation or the outcome, so you still file with the agency it names.
This article is general information, not legal, tax or investment advice. Figures and rules carry the year they were published; check the cited source for the current version.
Christian Eckmair is co-founder of CheckValue and managing director of CBDNOL GmbH (Ansfelden, Austria). He has worked in real estate for more than 20 years in Tenerife and Austria – buying, renovating, letting and selling residential property – and writes about home values, buying checks and ownership records.
Articles by Christian Eckmair →Follow: RSS · Feedly · Add as a preferred source on Google
Sources
- 1guidanceInteragency Guidance on Reconsiderations of Value of Residential Real Estate Valuations (89 FR 60549)Federal Register (OCC, Federal Reserve Board, FDIC, NCUA and CFPB) · 2024Published 26 July 2024; an ROV is a request from the financial institution to the appraiser or other preparer to reassess the report based on potential deficiencies or other information that may affect the value conclusion; valuations may be deficient due to errors or omissions; an ROV request may include property characteristics incorrectly reported or not previously considered; examples of policies include informing consumers how to raise concerns early in underwriting and checking for unreasonable barriers; scope limited to transactions secured by a single 1-to-4 family residential property; supervisory guidance without the force of law.govinfo.gov ↗
- 2officialGrievance procedures (contesting your assessment in New York State)New York State Department of Taxation and Finance · 2026Any person who pays property taxes may grieve an assessment; only the assessment on the current tentative roll can be grieved; Form RP-524 outside New York City and Nassau County; Grievance Day is usually the fourth Tuesday in May; no cost and no lawyer required; the complainant may present statements and documentation to the board of assessment review and receives a written decision.tax.ny.gov ↗
- 3officialOwner, Taxpayer and Address ChangesSnohomish County Assessor, Washington · 2026Owner name records on the joint assessor and treasurer website are taken from the Real Estate Excise Tax (REET) form filed with the recorded documents; after the sale is recorded and the REET paid a copy of the form is sent to the assessor; it may be a few weeks before staff process and update the owner name, and the change may be delayed even longer when only a portion of the property actually sold; errors in the owner's name are handled by the Auditor's Office and errors in the physical description through the Assessor's Office; ownership records for legal purposes (deeds, real estate contracts) are recorded in the Recording Division of the county Auditor's Office.snohomishcountywa.gov ↗
- 4statisticsHouse Price IndexFederal Housing Finance Agency (FHFA) · 2026A weighted repeat-sales index measuring average price changes in repeat sales or refinancings on the same properties, published at national, census division, state, metro area, county, ZIP code and census tract level.fhfa.gov ↗
- 5law12 CFR 1002.14, Rules on providing appraisals and other valuations (Regulation B)Electronic Code of Federal Regulations, Consumer Financial Protection Bureau · 2024A creditor must give the applicant a copy of every appraisal and other written valuation developed for credit secured by a first lien on a dwelling, promptly upon completion or three business days before consummation, at no charge, with written notice of that right within three business days of application.ecfr.gov ↗
- 6officialFrequently Asked Questions, Appraisal Complaint National HotlineAppraisal Subcommittee (ASC) · 2026Users are provided with the contact information for the State and/or Federal agency that should receive their complaint; the hotline covers alleged non-compliance with USPAP and alleged non-compliance with appraisal independence standards, including improper influencing of appraisers or the appraisal process; representatives answer on 877-739-0096 Monday through Friday; the ASC has no legal authority to investigate complaints and the hotline does not intervene with the complaint process, investigation, or final outcome.refermyappraisalcomplaint.asc.gov ↗
- 7statisticsFHFA House Price Index Up 0.3 Percent in July; Up 2.6 Percent from Last YearFederal Housing Finance Agency (FHFA) · 2026Release of 29 September 2026: US house prices up 0.3 percent in July and 2.6 percent from July 2025; twelve-month changes by census division ranged from 0.6 percent in the Mountain division to 6.3 percent in the Middle Atlantic division.fhfa.gov ↗
- 8law15 U.S.C. 1681b, Permissible purposes of consumer reportsLegal Information Institute, Cornell Law School · 2026Lists the purposes for which a consumer reporting agency may furnish a consumer report, including credit transactions, employment purposes and insurance underwriting.law.cornell.edu ↗